What is the scope and industry significance of the Cloud-Based Rental Management Platforms Market?
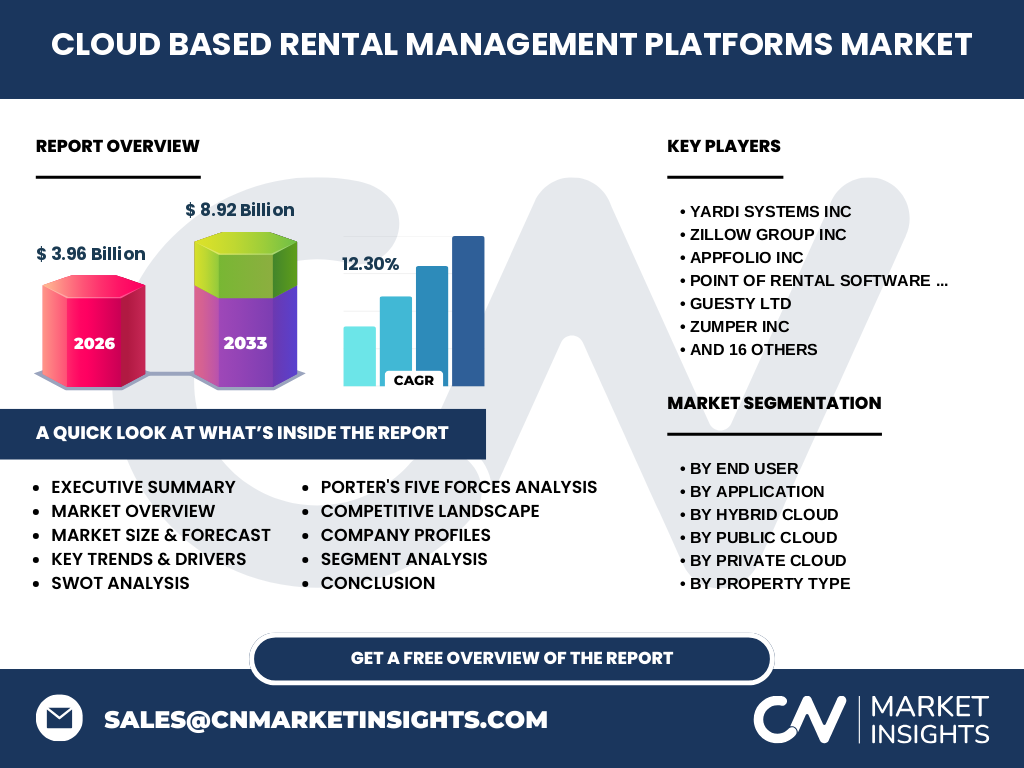
The Cloud-Based Rental Management Platforms Market represents a critical digital transformation vector for real estate. Currently valued at 3.96 Billion in 2026, these platforms centralize lease, accounting, and compliance operations. By leveraging SaaS-based architectures, providers like Yardi Systems Inc and AppFolio Inc allow stakeholders to streamline asset lifecycles, significantly reducing manual overhead in property management and improving overall operational liquidity across residential and commercial sectors.
Structural Growth Drivers and Market Constraints
Growth is primarily propelled by the 12.30% CAGR, fueled by the digitization of rental workflows. While scalable resource management offers immense opportunities, the industry faces hurdles from stringent local regulatory frameworks regarding data sovereignty. Furthermore, the reliance on high-speed internet connectivity creates geographical deployment constraints for firms like Point of Rental Software Inc, necessitating robust hybrid cloud strategies to maintain data integrity and user uptime.
Emerging Trends Shaping Industry Trajectories
The market is witnessing a profound shift toward multi-tenant deployment architectures, prioritizing optimized cost structures for users. Companies such as Guesty Ltd and DoorLoop Inc are leading this trend by integrating advanced analytics to assist property investors. These tools enable real-time financial reporting and automated lease management, which are increasingly vital as owners seek to maximize yield in a volatile macroeconomic climate.
How did COVID-19 redefine the Cloud-Based Rental Management Platforms Market?
The pandemic served as a catalyst for digital adoption, forcing a rapid departure from paper-based rental systems. As lockdowns prevented manual site access, demand for remote service delivery surged. Post-recovery, this shift has solidified into a permanent trend, with Zumper Inc and TenantCloud LLC capturing market share by facilitating contactless leasing and digital compliance management, which are now standard expectations within the rental ecosystem.
Competitive Benchmarking and Market Concentration
The landscape is highly fragmented, characterized by a mix of specialized vendors and broad enterprise providers. Major players like Entrata Inc and Yardi Systems Inc focus on large enterprise clients, while TurboTenant Inc and Baselane Inc. target the SMB segment. Strategic dynamics are currently defined by aggressive M&A activities and product differentiation, particularly regarding the ease of on-demand resource scaling.
Executive Summary: Key Findings and Market Outlook
Our research identifies that the sector is set for explosive growth, with valuations projected to reach 8.92 Billion by 2033. The confluence of integrated public and private cloud environments, alongside a surge in vacation rental management demand, positions the market for sustained expansion. Strategic success in this space now depends on seamless API integrations and the ability to offer highly customizable, secure, and compliant cloud configurations.
Market Forecast: 2027 to 2033
Projections indicate the industry will experience a robust 12.30% CAGR throughout the forecast period. We anticipate the valuation will climb from 2027 levels toward the 8.92 Billion target by 2033. This growth trajectory is supported by increased cloud penetration across emerging markets and the continued scaling of subscription-based access models, which lower the barriers to entry for independent property managers.
Segmentation Analysis: Driving Value through Specialization
Segmentation is categorized by end-user, application, and deployment. Property Managers and Agents represent the primary revenue drivers, while compliance management modules have become indispensable. Furthermore, the choice between Public, Private, and Hybrid clouds allows firms to balance cost and control. EZRentOut Inc and HireHop Ltd illustrate how specialized deployment strategies—such as dedicated infrastructure for sensitive data—are essential for meeting diverse client requirements.
Geographic Performance: Regional Market Analysis
Regional performance is dictated by local real estate density and broadband availability. North America remains the dominant revenue generator, benefiting from a high density of large-scale enterprise property firms. However, Europe and Asia-Pacific are emerging as high-growth hubs, where regulatory bodies are increasingly incentivizing the digitization of tenant management, fostering a surge in localized demand for flexible, secure, and scalable cloud-based solutions.
In-Depth Regional Review
The North American market leads due to established SaaS infrastructure and mature rental models. In contrast, the European market places a higher premium on data segmentation and control, aligning with GDPR-like privacy standards. Companies like Booqable B.V. and HireHop Ltd have tailored their strategies to these specific regulatory environments, ensuring that their software meets regional compliance while maintaining a global competitive edge.
Strategic Positioning of Leading Companies
Companies are segmenting the market based on technical capability. Yardi Systems Inc and Entrata Inc focus on enterprise-grade reliability and deep financial reporting suites. Conversely, Flex Rental Solutions Inc and Quipli Inc lean into flexible workload distribution and user-friendly interfaces. This strategic bifurcating allows vendors to compete effectively, whether by serving massive residential portfolios or catering to the specific needs of niche vacation rental providers.
Porter's Five Forces Analysis
The threat of new entrants is moderate, mitigated by the high technical barrier of maintaining secure cloud infrastructure. Competitive rivalry is intense, with firms like Rentec Direct LLC and Landlord Studio Pty Ltd battling for market share via feature innovation. Buyer power is high due to low switching costs, while the threat of substitutes remains low, given the increasing reliance on digital, internet-based service delivery models.
SWOT Analysis of the Cloud-Based Rental Management Platforms Market
Strengths: Massive scalability and automated workflow efficiency. Weaknesses: High initial reliance on reliable internet access. Opportunities: Integration of AI-driven tenant risk assessment and smart home IoT connectivity. Threats: Rising cybersecurity risks and evolving global data protection legislation. Firms like MagicDoor Inc demonstrate resilience by focusing on controlled access environments, effectively turning potential security threats into a key platform strength.
Value Chain Analysis: From Infrastructure to End-User
The value chain initiates with Cloud Infrastructure Providers, who supply the raw data centers and bandwidth. These resources are utilized by rental platform developers to build software, which is then distributed via subscription models. The chain concludes with end-users (property investors, associations), who derive value through optimized rental accounting, improved tenant communication, and automated compliance, creating a continuous loop of software performance feedback.
Investment Insights and High-Potential Areas
Investors should prioritize companies demonstrating scalable resource management capabilities and strong Multi-Tenant architectures. High-potential areas include platforms that integrate directly with local financial institutions or regulatory reporting software. Strategic investments in vendors like SimplifyEm LLC or those focused on niche commercial assets are particularly attractive, as these platforms offer higher margins and deeper integration into the user's daily operations.
Conclusion and Key Takeaways
The Cloud-Based Rental Management Platforms Market is an essential pillar of modern property management. With a projected growth to 8.92 Billion by 2033, the industry is transitioning from manual, disparate systems to unified digital ecosystems. Success will favor organizations that prioritize data security, user-friendly automation, and the ability to adapt to complex, localized regulatory compliance environments worldwide.
Research Methodology: Triangulation of Market Data
Our estimates are triangulated using a multi-layered approach. We combine trade registry data, primary stakeholder interviews with industry CTOs, and macroeconomic indicators. We cross-reference platform adoption rates from major providers against national rental market statistics to ensure accuracy. This rigorous, evidence-based methodology allows us to provide a high-fidelity outlook on market valuation, CAGR, and segment distribution within the rental technology sector.
Scope of the Report and Coverage Parameters
This report covers the global landscape of rental management software, focusing on end-user categories including residential, commercial, and vacation segments. The scope is limited to cloud-based deployment models—Public, Private, and Hybrid. Excluded are on-premise legacy systems, which fall outside the modern SaaS paradigm. Our analysis provides a comprehensive view of the market from 2026 to 2033, focusing on technology, adoption, and competitive strategy.
Recent Developments: Announcements and Partnerships
The sector is currently defined by rapid innovation. Recent announcements show an increase in strategic partnerships between cloud platforms and property insurance providers. Furthermore, companies like TapGoods Inc and Booqable B.V. have launched enhanced subscription-based access features, streamlining the rental process for specialized assets. These moves indicate a market-wide focus on maximizing asset utility through expanded service integration and improved user experience.